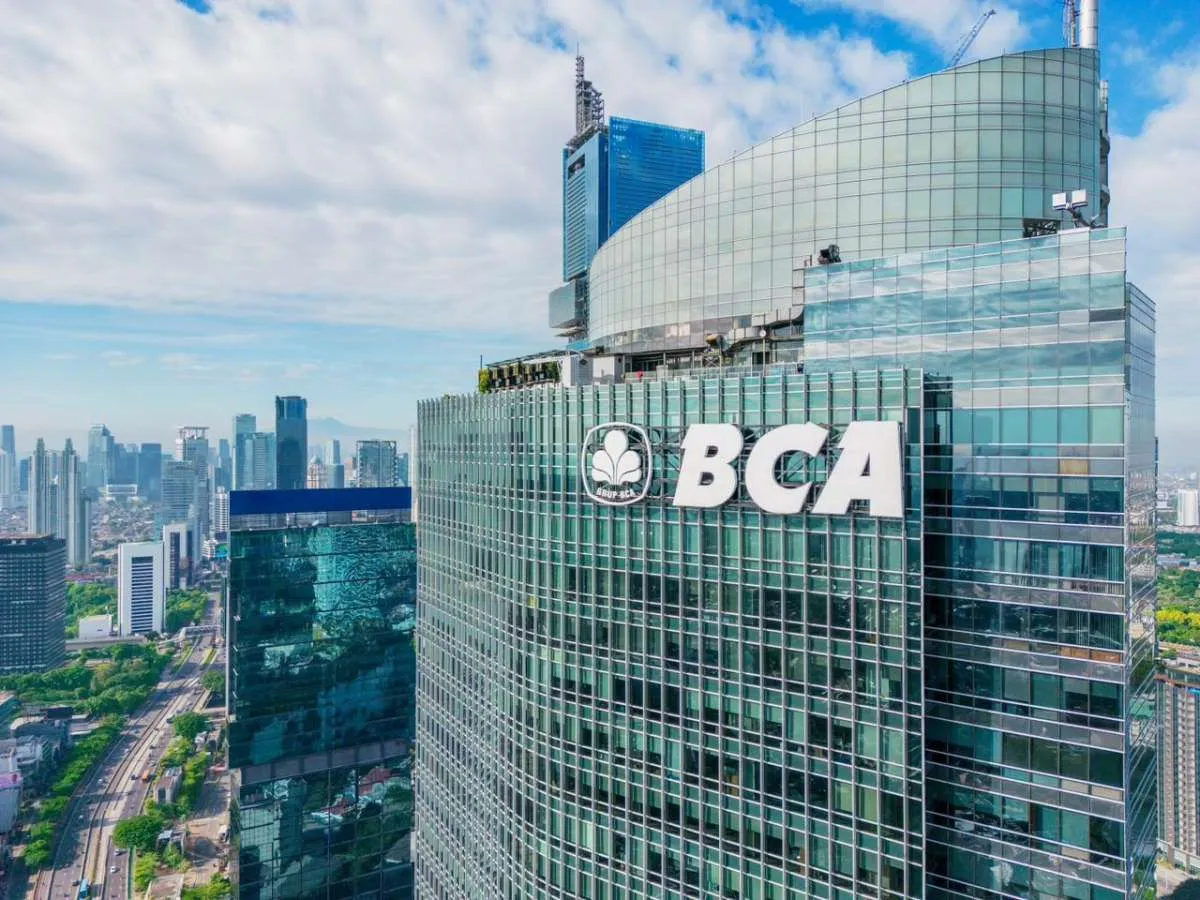
STOCK MARKET - Southeast Asia’s premium banking heavyweight, PT Bank Central Asia Tbk (BCA), has successfully sustained its operational momentum through the first eight months of the year, crossing a major profitability milestone despite tightening margin compression across emerging market financial networks.
According to the lender's monthly bank-only financial statement released on Tuesday (15/9/2026), the lender—traded under the ticker BBCA—pocketed a net profit of IDR 40.17 trillion up to August 2026, marking a modest 2.85% year-on-year (YoY) increase.
The steady performance was cushioned by Net Interest Income (NII), which edged up 1.33% YoY to reach IDR 53.82 trillion.
Read Also: Ousted Indonesia Finance Minister Says He was 'Upset', but Half Expected Removal
Navigating Rising Funding Costs and Impairment Cuts
While gross interest income climbed 2.42% YoY to IDR 62.86 trillion, the tier-one bank faced substantial pressure from its liability side, with interest expenses surging by 9.4% YoY to IDR 9.04 trillion. This spike highlights the broader macroeconomic drag of high interest rates on funding costs.
To offset this margin squeeze, BBCA leveraged its stellar credit risk mitigation and fee-based income pipelines:
- Impairment Provisions: Slashed significantly by 18.55% YoY down to IDR 2.16 trillion, freeing up internal capital.
- Fee and Administration Revenues: Expanded solidly by 7.74% YoY to IDR 13.59 trillion.
- Financial Asset Sales: Jumped by a massive 71.42% YoY to bag IDR 1.81 trillion.
These defensive maneuvers successfully insulated the bank's core operations, keeping overall operating profits in expansion territory at IDR 49.36 trillion, up 2.72% YoY.
Read Also: GLOBAL MARKETS-Asian Shares Waver as Oil and Yields Rise Ahead of Fed, BOJ Meetings
Double-Digit Loan Expansion and CASA Dominance
For international equity desks tracking Indonesia's economic engine, the highlight of the report rests on BBCA's aggressive credit intermediation. Total outstanding bank-only loans breached the IDR 1,017.7 trillion mark, posting a powerful 10.52% YoY growth. This lending surge expanded the bank's total asset footprint by 8.19% YoY to a massive IDR 1,596.96 trillion.
On the funding side, Third-Party Funds (DPK) grew 8.33% YoY to IDR 1,256.83 trillion, anchored heavily by Current Account and Savings Account (CASA) dominance. Current accounts (giro) led the influx with a 14.73% YoY explosion to IDR 447.5 trillion, while savings (tabungan) grew 8.2% YoY to IDR 626.69 trillion. Conversely, high-cost time deposits fell 4.3% YoY to IDR 182.62 trillion, proving that retail depositors are favoring liquidity over fixed yields.
This dynamic efficiently optimized the bank's capital efficiency, pushing its Loan-to-Deposit Ratio (LDR) up to a healthy 80.97% from the prior year's 79.38%. For global asset managers holding emerging market financial portfolios, BBCA’s ability to drive double-digit credit growth while managing a low-cost deposit framework cements its status as a defensive benchmark play over the multi-year investment horizon.
Read Also: Nvidia’s Huang Backs Trump to Keep US Ahead of China in AI Tech Race