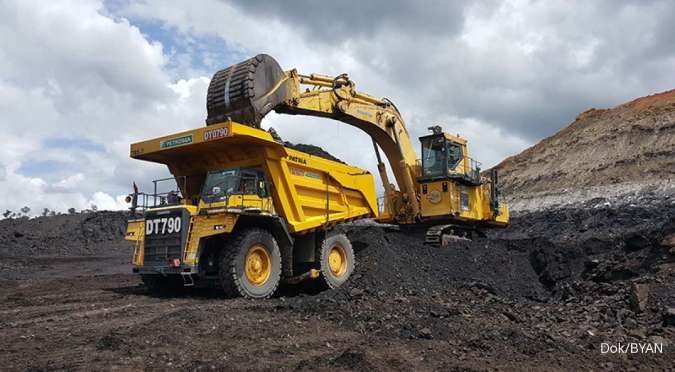
RATING MOODY'S - Global rating agency Moody’s Ratings has downgraded the credit outlook of Indonesian coal mining giant PT Bayan Resources Tbk (BYAN) to Negative from Stable, citing heightened sovereign regulatory uncertainty surrounding annual production quotas.
While the agency successfully affirmed BYAN’s Corporate Family Rating (CFR) at Ba1, the outlook revision directly follows the conglomerate's formal invocation of a force majeure clause on September 14, 2026.
Anthony Prayugo, Assistant Vice President at Moody’s Ratings, confirmed that extended administrative delays by the Indonesian government in greenlighting BYAN's revised annual mining work plan and budget (RKAB) have severely restricted the company's near-term output visibility.
Read Also: Bayan’s Low Tuck Kwong Signs 10 Billion Share Sale to Jhonlin Baratama
Production Paralyzed: A Projected 42.6% Volume Collapse
Moody’s warns that if central regulators freeze the current quota expansion requests, the thermal coal titan's 2026 production volume will collapse by 42.6% to settle at approximately 39 million metric tons (MT), down sharply from the 68 million MT extracted in the previous fiscal year.
- 2025 Baseline EBITDA: Logged at approximately US$1.1 billion.
- Projected 2026 EBITDA (No Quota Boost): Forecast to tumble by 36.3% to US$700 million due to lower shipping allocations.
- Projected 2027 EBITDA: Risking a further slide down to US$400 million–US$500 million, utilizing a conservative average selling price (ASP) assumption of US$48 per MT.
- The downgrade serves as a stark contrast to initial institutional assumptions, which positioned BYAN to steadily expand output toward its full-scale 80 million MT capacity threshold.
Read Also: Global Crackdown: EU and US Tighten Social Media Bans for Minors
Debt-Free Balance Sheet Cushions Systemic Downside
Despite the acute regulatory drag hitting the revenue engine, Moody’s emphasized that BYAN’s underlying credit metrics remain exceptionally defensive. The mining firm operates a high-liquidity, zero-debt balance sheet, allowing it to fully bankroll its multi-year capital expenditure (capex) and corporate dividend distributions through internal cash generation rather than drawing down external debt facilities.
Consequently, the company's adjusted debt-to-EBITDA leverage ratio is legally insulated, projected to remain safely below 0.5 times over the next 24 months. Furthermore, BYAN maintains excellent liquidity buffers over the 18-month holding horizon, backed by US$650 million in unutilized, committed working capital credit facilities from tier-one banks as of late June 2026.